


Blueprint 2026 and the Physical Side of AI in Real Estate
The largest operators already run AI in production. For the rest of the market, and for the data centers AI depends on, many of the open questions are operational and physical.
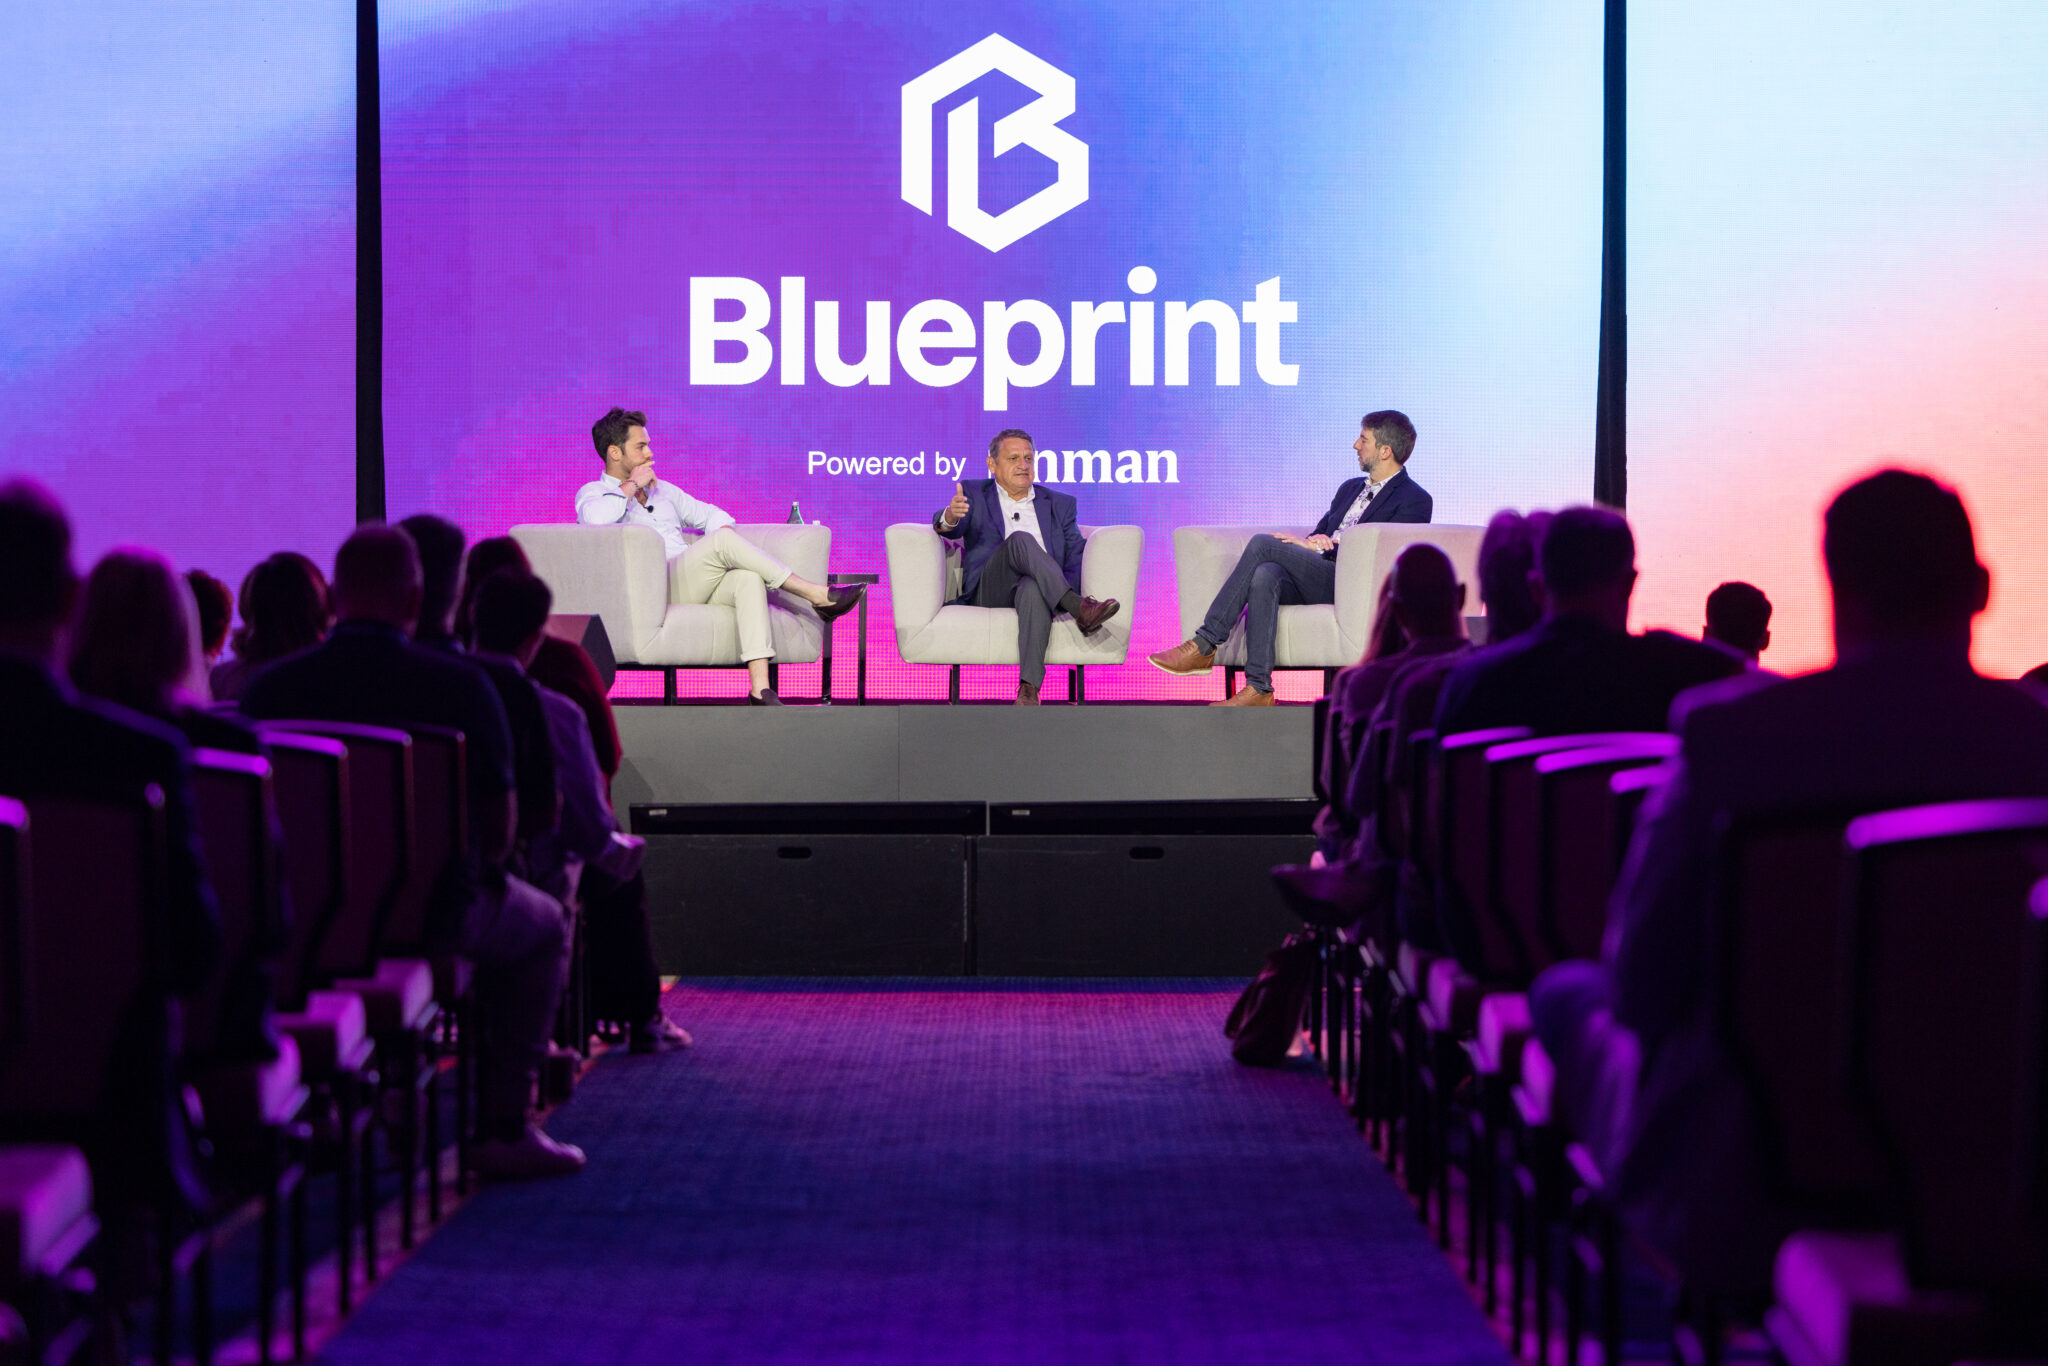 Photo: Blueprint
Blueprint brings together many of the owners, operators, builders and developers who buy technology, which makes it a good place to gauge how AI adoption in real estate is actually going.
This year, the most visible progress came from large residential operators, several of which described AI already running across their businesses. For most of the industry, the harder work is making a new system function inside an existing operation, and that work often leads back to the physical asset. An older building may not support new equipment without a costly upgrade, a homebuilder cannot break ground until its plans are permitted, and much of the work depends on skilled trades.
The data center sessions, where AI is the source of demand rather than the tool, raised many of the same constraints at a much larger scale. Software remains central to how the industry is changing, but these physical and operational factors increasingly shape how quickly it can be used, and they create room for companies that address them directly.
From pilot to operation
Two single-family rental operators showed what that looks like. Progress Residential operates nearly 100,000 homes across more than 30 markets with no leasing offices and no on-site staff, and its session covered the agentic AI it uses in leasing and maintenance. At AMH, which runs 60,000 homes, CEO Bryan Smith described AI in leasing, HOA documentation and technician scheduling, including a leasing deployment whose return the company could measure.
Survey data suggests how much ground remains for the broader market. JLL’s 2025 Global Real Estate Technology Survey looked at corporate real estate occupiers, a different group from residential operators, and found that most were running AI pilots while far fewer had reached their program goals.
| Corporate real estate occupiers | Share reported by JLL |
|---|---|
| Running AI pilots | 92% |
| Achieved two to three AI program goals | 47% |
| Achieved all AI program goals | 5% |
Since operators largely have access to the same models, the distance between a pilot and a working system is mostly about how well a product fits the way a company already operates. One multifamily session was devoted to what operators had deleted this year, from retiring legacy software and consolidating platforms to reducing logins. When operators are trying to cut the number of systems their staff must use, a new product is judged partly on whether it replaces something and whether it can run across a portfolio without a fresh implementation at every property.
Older buildings and unbuilt homes
In existing buildings, the constraint is often economic before it is technical. A panel titled “Smart or Just Expensive?” asked whether the smart features added to apartments over the years have actually improved operations and net operating income. One of the panelists, Asset Living’s Nikki Ganier, described the difficulty of retrofitting older Class B and C properties when new power and infrastructure costs are not supported by enough additional rent. For many older properties, that calculation settles the question before any product is evaluated. Software-only and sensor-light products that need no new power or wiring can reach owners who would not approve a major installation.
In homebuilding, much of the delay sits before construction begins. Shanna Tellerman, who was Lennar’s chief product officer before founding Geom, spoke at Blueprint about how that experience is shaping her new company. Large builders keep many plans current by region, and construction cannot start until the plan set is complete and permitted. Geom is developing software to automate the detailing that turns schematic designs into construction-ready documents. When design work affects the timing of a project, improving it can influence when construction begins and how long capital remains committed before revenue starts.
AI as a source of demand
Digital Realty CEO Andy Power joined Fifth Wall’s Brendan Wallace on the main stage for “Powering the AI Boom,” a session built on the premise that the binding constraints on data centers are now land, power and capital rather than demand. The speakers listed for a separate panel on data center construction included Les Karpas, who leads physical AI for NVIDIA’s Inception startup program, alongside executives from a general contractor and a modular infrastructure company. The panel was organized around grid access, cooling, supply chain, labor and prefabrication.
The scale is substantial. JLL’s 2026 outlook projects global data center capacity rising from 103 gigawatts to about 200 gigawatts by 2030. In the United States, Berkeley Lab’s updated energy-use report puts electricity demand in its 2030 reference case at more than three times its estimate for 2024.
U.S. data center electricity demand
Annual electricity use, terawatt-hours (TWh)
1922024
4642028E
6492030E
Source: Berkeley Lab, 2025 update. 2024 is a historical estimate; E denotes a reference case forecast.
Berkeley Lab’s 2030 scenarios range from 521 to 843 terawatt-hours, and where and when that demand arrives will matter as much as the total. Even the low end is more than two and a half times the 2024 estimate. Because data centers draw on the same contractors and workers as other construction, their pace can also affect costs and schedules elsewhere in real estate.
The companies serving this demand will include energy and construction businesses as well as software, so a venture investor can find opportunities around the AI buildout without underwriting every company as an AI software business. The relevant expertise may sit in engineering, project delivery or the relationships needed to bring infrastructure into operation.
Where new companies fit
Four areas seem especially open to new companies. The first is pre-construction and entitlement, where shortening the path from schematic design to permitted plan changes when a project can start. The second is retrofit economics, meaning products that raise what an older property can support without new power or wiring. The third is energy and interconnection, including on-site generation, thermal management and demand flexibility, which affect whether and when projects proceed, for an older building adding load as much as for a data center.
The fourth is trade labor productivity. Labor appeared throughout the agenda, and credible answers remain rare. Construction, maintenance and data center delivery all depend on skilled trades, so progress there would be felt well beyond any one asset class.
The pace of adoption
These companies are selling into a tighter market. Freddie Mac’s average 30-year fixed mortgage rate reached 7.03% on September 24, the last day of Blueprint and its first reading above 7% since January 2025. A week later it was 7.28%. Higher rates raise the cost of carrying land and projects, and owners tend to respond by scrutinizing new spending. Session titles such as “Non-Hype AI” and “From Data to Dollars” pointed in the same direction. Some good products will take longer to sell, while those with a clear effect on operating income or a project’s schedule should have an easier time.
Away from the stage
As usual, some of the most valuable conversations happened away from the stage. It was good to spend time with friends at JLL Spark and Suffolk Technologies, and with executives from PRODA and LMRE. JLL Spark invests from inside one of the largest commercial real estate services firms, and Suffolk Technologies from inside a general contractor that has to put buildings in the ground. PRODA works on rent roll data, and LMRE on recruiting across the industry.
Blueprint returns to The Venetian on October 26 to 28, 2027. Many of these constraints will likely still be on the agenda. The companies worth watching between now and then are the ones that make one of them easier to manage.